Category0

Midterm Madness and Hot CPI – Do Choppy Waters Lie Ahead?

The market is pulling back due to a hot inflation reading, and in our opinion the midterm elections are playing a part in the selloff as well. I don’t expect much upward movement over the next three weeks until the midterm is finalized, but from our viewpoint the trend is still healthy, and the market is still strong.

In our opinion, Mastercard (MA) edged above a buy point Tuesday, while rival Visa (V) moved higher into the buy zone. The two leaders are driving the payments industry to a market-leading position. Also we are looking at Ligand Pharmaceuticals Inc. (LGND), which has formed a cup-and-handle pattern. We think a move above $318.00 would indicate a breakout.
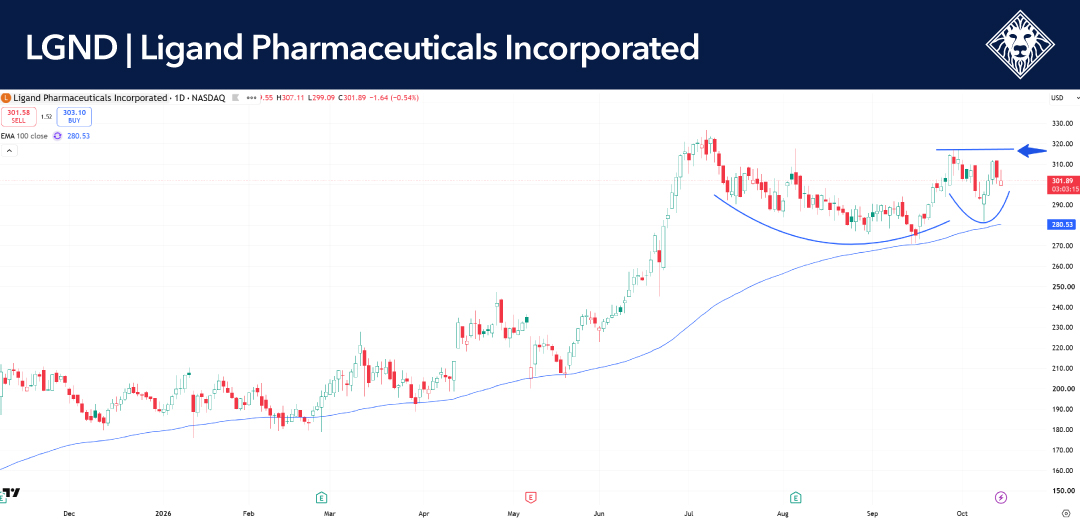
10-14-26-LGND

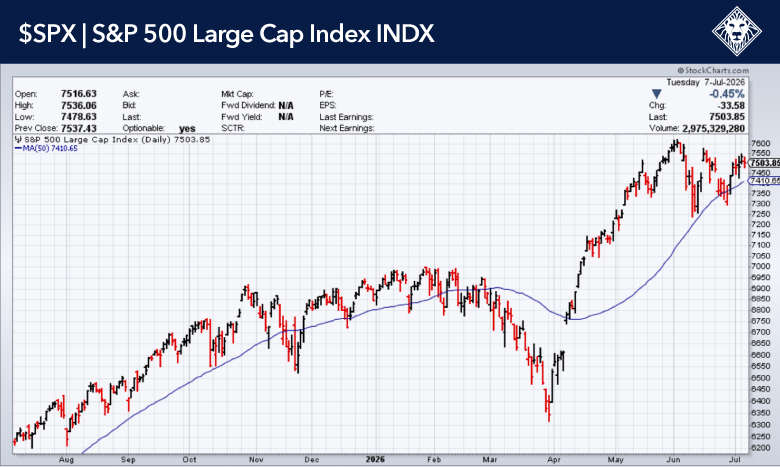
The consumer price index for September showed a bigger-than-expected increase in core prices, helping keep alive the chance of an Oct. 28 Federal Reserve rate hike. The S&P 500 turned lower while Treasury yields jumped after the CPI inflation data.
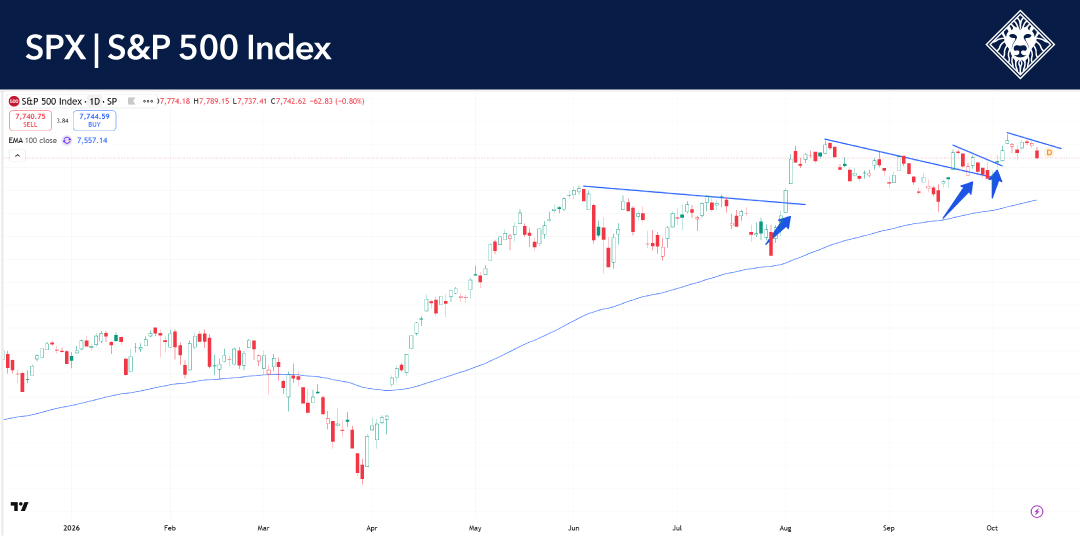
10-14-26-SPX

After the pickup in core CPI inflation, markets are pricing in 44% odds of a quarter-point Fed rate hike on Oct. 28, about double the odds just before the economic release. Markets now see 96.5% odds of the Fed hiking by 25 basis points up through the Dec. 9 Fed meeting. Odds of an additional 50 basis points in hikes by the end of the year climbed to 46% from just 18%.
Building Bulls – Are Factories Funding A Q4 Tech Rally?

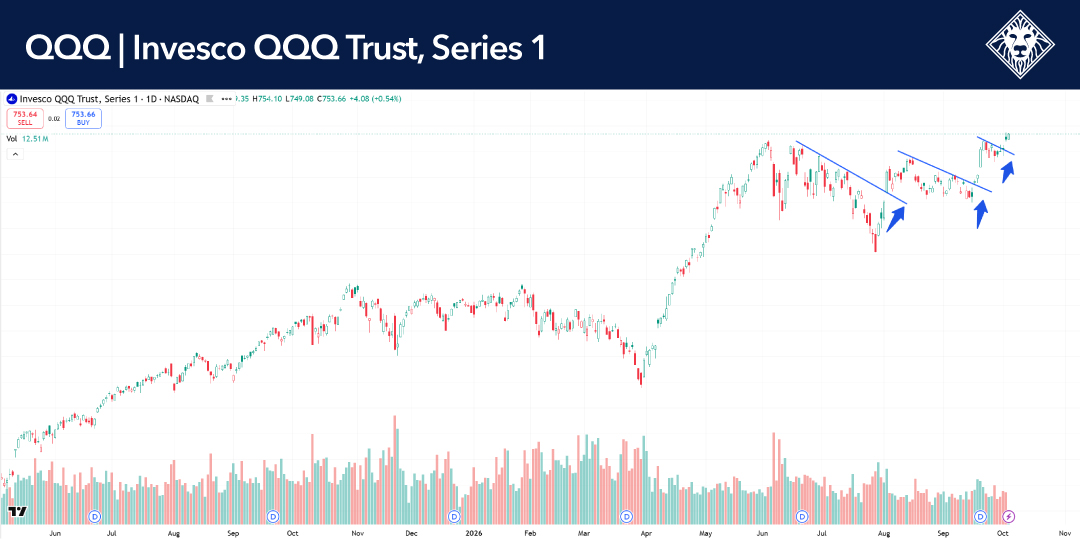
10-5-26-QQQ

The Nasdaq continues to march higher, and after breaking resistance several times we think it is in a good position to move higher. Mid-term elections are coming up, and this will in all probability add a bit of volatility, but we still see the market pushing higher into the last quarter of the year. Yields continue to rise, putting a lot of pressure on bond prices.

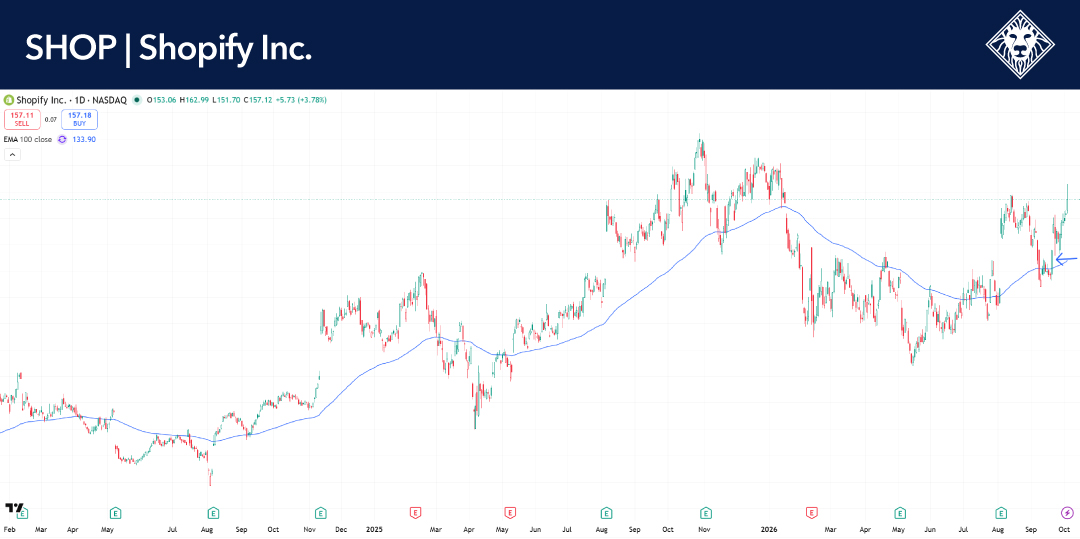
10-5-26-SHOP

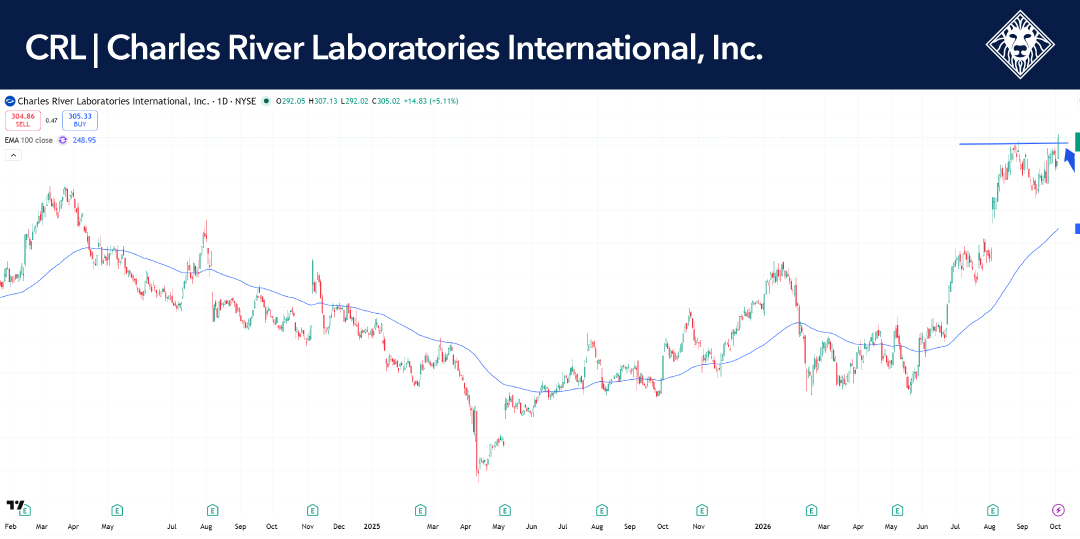
As you will recall from our last Wealth Watch, we wrote about Shopify, Inc. (SHOP). After coming down and touching its 100 DMA, the stock is doing well. Another stock that looks like it could be ready to move higher is Charles River Laboratories International, Inc. (CRL).

10-5-26-CRL

The manufacturing sector has gained significant momentum this year, supporting the overall economic expansion. In the update for September, the ISM Manufacturing PMI edged down 0.1 point to a slightly below consensus reading of 54.5. But it has been above 50 for all of 2026 to date and has averaged 54.9 in Q3, the highest level since mid-2022. Growth has also broadened, with more than 2/3 of subindustries reporting gains in the past several months, which bodes well for the sustainability of expansion.

While manufacturing accounts for a modest ~10% of GDP, its cyclical nature often dictates the direction of the overall business cycle. The latest readings suggest that economic growth has heated up in Q3. Importantly, it is a tailwind to corporate earnings growth, implying a fundamental support to the bull market in equities.


Skynet, Oil Spikes, and Rate Hikes: Cue the Year-End Rally?

The market has pulled back with news that AI could get out of control, rising oil prices, and the likelihood that the Fed will raise rates this week. Three negatives combined to put downward pressure on investors. However, we believe the market is reaching oversold conditions, so we hope to find an area of support soon. In other words, we see this as a buying opportunity.

This is nothing new on AI, but I think the bigger eye-opener is a bit different than most, including myself, thought. Many people thought that it would cause massive unemployment, which as time passes, does not look to be the case. Their fears, as we are learning, are more along the lines of AI taking over the codes for nuclear weapons, cyber-attacks, shutting down the electrical grid, and the list goes on. The talk over the weekend was about governments around the world who need to step in and build guardrails, so to speak. We will save everyone the suspense; governments will not step in until it blows up in everyone’s face. So, if you do not have some form of risk management system like the HCM-BuyLine®, for Heaven’s sake get one!

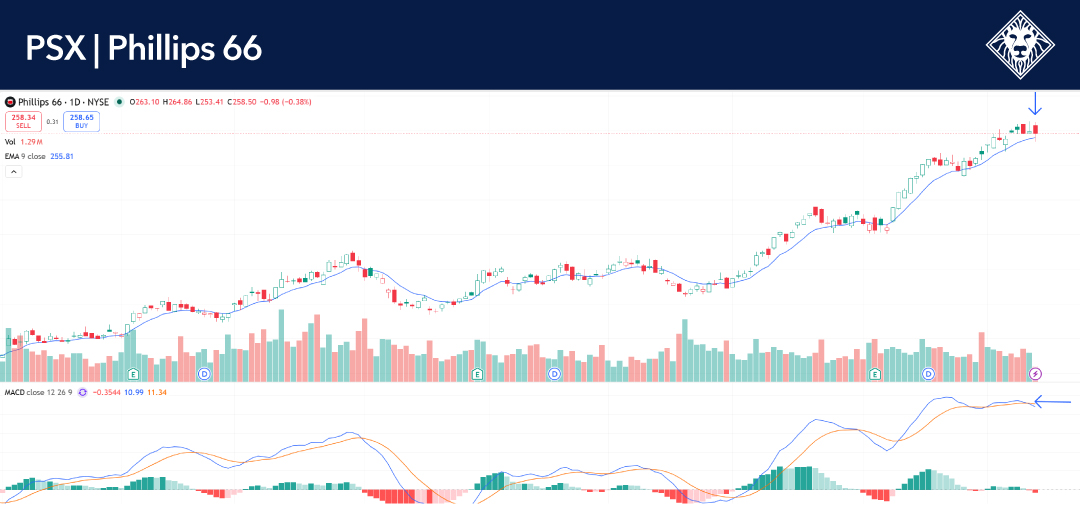
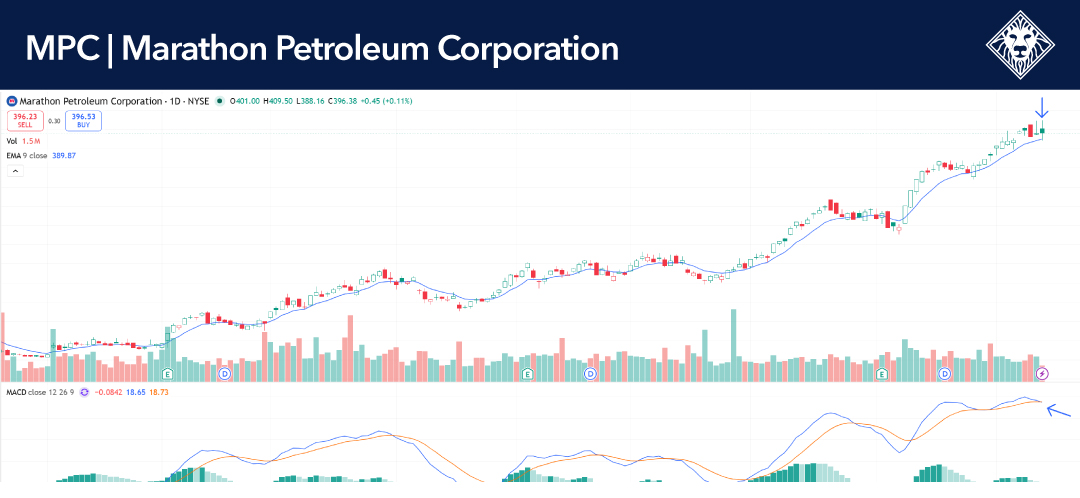
Oil prices have jumped, and several refiners, including Phillips 66 (PSX) and Marathon Petroleum (MPC), now look overbought and somewhat parabolic. Given the strength across the broader energy sector, we are looking to lock in profits in some of our energy holdings.

9-14-26-PSX
9-14-26-MPC

On the buy side, CrowdStrike Holdings, Inc. (CRWD) appears to be breaking out, and we believe it looks like they are ready to move higher. Shopify Inc. (SHOP) has pulled back to its 100 DMA and is building up momentum.

9-14-26-CRWD
9-14-26-SHOP

The new Fed Chair Warsh, in his last statement, has indicated a rate hike is in the cards this week, so we expect a quarter point rise in rates at the next Fed meeting.

But let’s close on a very optimistic note:

  • In the past 10 sessions, as all will know, oil has risen more than 20% while U.S. 10-Year Treasury Bond yields have risen more than 30 basis points. A rare circumstance.
  • Bond yields rising along with oil have caused a short-term drop, or a period of volatility, which corrected itself in 2 to 3 months followed by a very nice rally in stocks.
  • This has happened 12 times since 1983. Every single completed episode produced a positive SPX return at +12 months, ranging from +13.6% to +28.4%.

All that to say, we are looking for the market to be somewhat sloppy with a strong year-end rally.


Knock, Knock. Who’s There? An S&P 500 All-Time High?

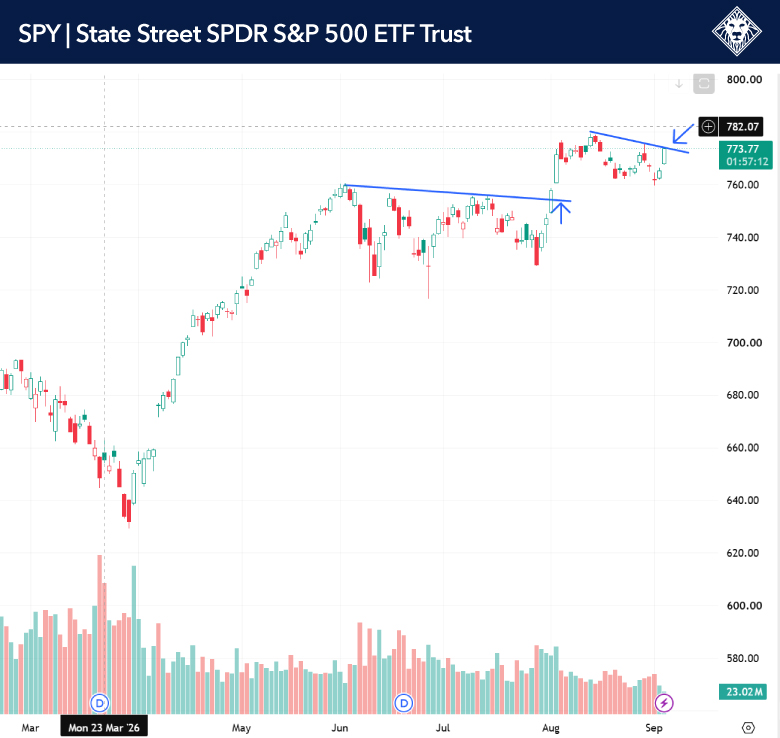
9-3-26-SPY

The S&P 500 broke out of resistance in early August and is now trying to push through another level of resistance. We believe a move above this level should lead to a new all-time high on the S&P 500.

9-3-26-CF

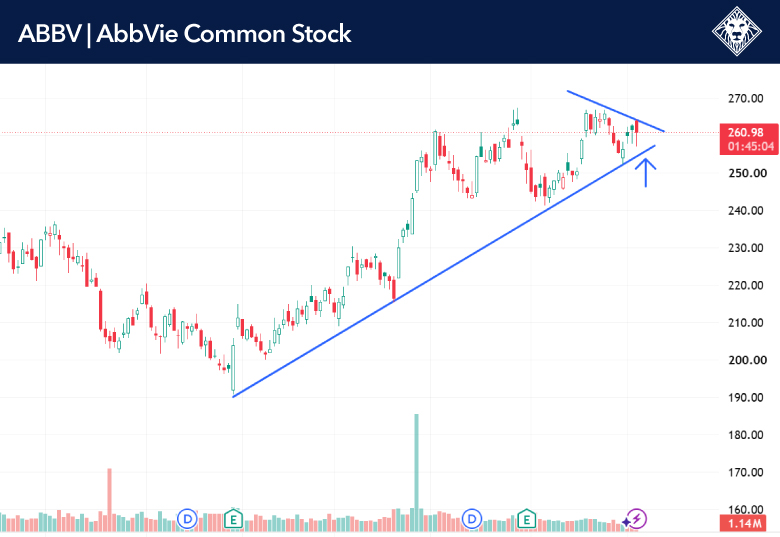
CF Industries (CF) is making a push to break out at $139.00, along with AbbVie Inc. (ABBV) at $264.00. Gold is holding and looks like it is ready to move higher.

9-3-26-ABBV
9-3-26-gold

The small-cap Russell 2000 index led the stock market higher on Wednesday even as the 10-year Treasury yield topped 4.8% for the first time since January 2025. The rebound in equities comes in the wake of Tuesday’s sharp losses that downgraded the market outlook.

The Russell 2000 rallied 1.1% on Wednesday while the Dow Jones Industrial Average followed up by rising 295 points, or 0.6%. The S&P 500 and the tech-heavy Nasdaq composite each moved up 0.5%. All four indexes snapped a run of three consecutive losses.

Investors started the session with labor-market data in hand. ADP said private payrolls rose by 38,000 in August, missing estimates that called for a gain of 48,000. August marked the slowest pace of job creation since January. The ADP jobs data is seen as a precursor to Friday’s jobs report from the Labor Department.

Economists widely anticipated a moderate gain of 55,000 in U.S. payrolls after a surprising 23,000 decline in July. The unemployment rate is expected to tick higher to 4.2% from 4.1% in July, per Econoday.


Hawks in the Fed, Bulls in the Market

8-18-26-SPX

The trend is up and any pullback should be considered buyable, in our opinion. The S&P 500 is trading around 7,700 and still looks like it could be headed to our target of 8,000 by year-end.

Earnings have been solid. Of the 454 companies that have reported so far (91% of the S&P 500):

  • Overall, 87% are beating estimates, and those that “beat” are beating by a median of 7%.
  • Of the 13% missing, those are missing by a median of -2%.
  • On the top line, overall results are beating estimates by a median of 4% and missing by a median of -3%, and 76% of those reporting are beating estimates.
8-18-26-LPG

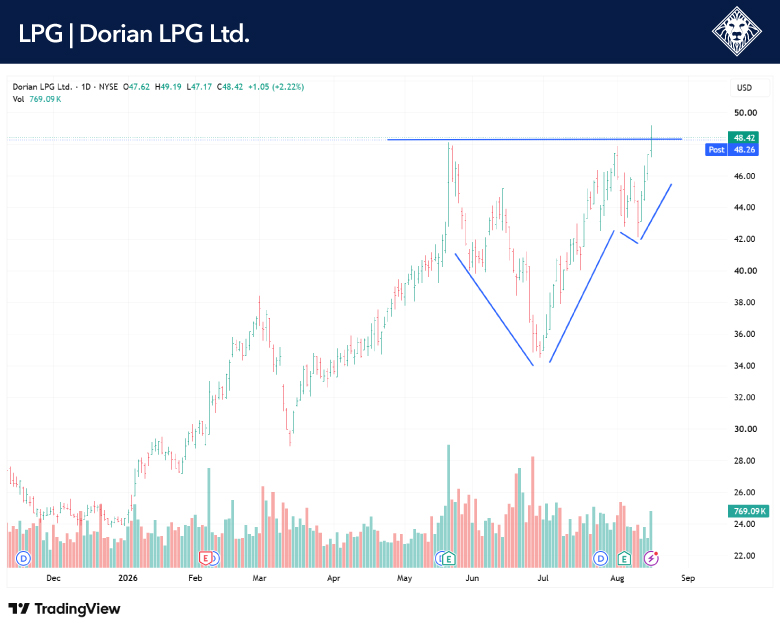
Dorian LPG Ltd. (LPG) broke out of a cup-and-handle pattern and looks like it could be moving higher. Also take a look at FedEx (FDX). We think a move above $344.00 would confirm a new breakout has begun.

8-18-26-FDX

West Texas Intermediate Crude futures were up nearly 3% in recent trading, rising to around $84.80 per barrel. Oil rose after Trump told Fox News that the U.S. would “bomb the s***” out of Oman if the country “gets in the way” of U.S.-Iran negotiations with their 60-day ceasefire expiring Monday.

Brent crude, the international energy benchmark, posted a similar gain to WTI and was up to $91.10 per barrel. Murban Crude jumped nearly 7% to trade at $95.45 per barrel. The latter is produced in Abu Dhabi and is a benchmark for Middle Eastern exports heading to Asian markets.

The 30-year Treasury yield climbed 4 basis points to 5.21% and the 10-year Treasury yield rose 3 basis point to 4.72%. Bitcoin was up nearly 2% to around $64,300 per token.

The minutes from the Federal Reserve’s policy meeting are set for release Wednesday. At that meeting, the Fed held its benchmark interest rate steady, but multiple dissents in favor of a rate hike support market expectations for a tightening of monetary policy in September.

Three members of the Fed policy-setting panel, the Federal Open Market Committee, or FOMC, dissented, preferring a rate hike. That made the vote 9-3 in favor of steady policy. That level of dissent is uncommon.


Next Stop 8,000? Why We’re Not Sweating the Summer Chop

The Nasdaq composite and artificial intelligence chip stocks staged a snapback rally Thursday following the market’s battering by renewed U.S.-Iran hostilities and the aftermath of the Federal Reserve’s decision to leave interest rates steady. We think the AI trade has sold off enough at this point, with a lot of AI stocks giving back 50% or more of their gains. The much-discussed leverage has finally pulled back, and we believe volatility is going to be here for a couple more weeks, probably into mid-August. Will the AI stocks shoot back up to their all-time highs? We think the odds are slim, but if they do, they will most likely start to work their way back up at a more measured pace, with a more normal trading pattern. The market has broadened out, and we expect the index to move higher, especially in Q4. Our target for the S&P 500 is still to get close to, if not exceed, 8,000.

Three stocks to watch:

Amgen (AMGN) – look for a break above $401.00

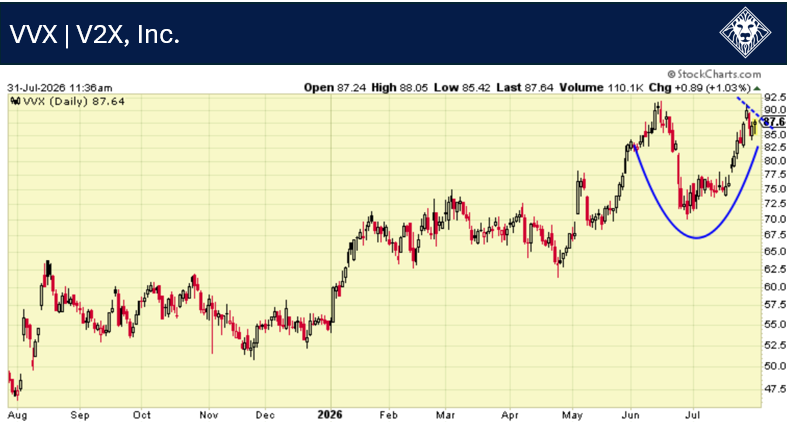
V2X (VVX) – look for a break above $91.00

Murphy USA (MUSA) – look for a break above $630.00

U.S. real growth surprised to the downside, but the underlying demand is strong. Real GDP increased at a 1.5% annualized rate in Q2, below the consensus and the prior quarter’s 2.1% growth rate. Stronger consumer spending and continued capex growth were positive drivers, while net exports, inventories, and the government sector were drags.

Final sales to domestic purchasers, which excludes net exports and inventories, rose at a 3.1% annualized rate, the most since Q3 2024, and above the long-run average of 2.8%, indicating strong domestic demand. Final sales to private domestic purchasers, which also excludes the government sector, rose at an even stronger 3.9% annualized rate, the most in over three years. Such buoyant domestic demand is keeping inflation pressures elevated.


Small Caps, Big Moves, and Tech On Sale

7-28-26-COMPQ

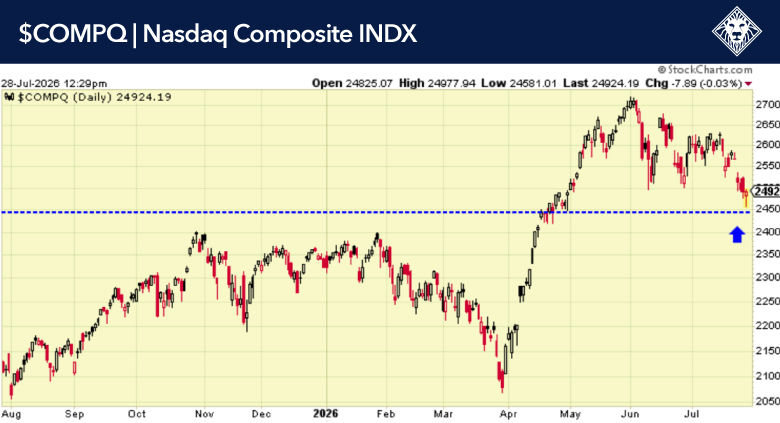
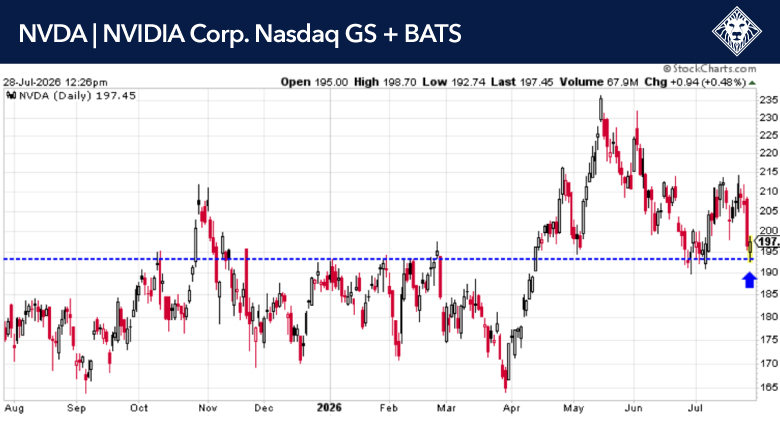
Investors appear to be more focused on corporate earnings than rising oil prices, Treasury yields, and gold. But the focus could shift back to the broader macro picture when the Federal Reserve meets on July 29. The Nasdaq-100 sank to an intraday low of 27,452.95, which was nearly 11% below its record high of 30,762.20, putting it in correction territory. We see this as a buying opportunity in semiconductors and the NASDAQ, which have both pulled back substantially after a large run up. We feel this is not the end, but the beginning.

7-28-26-SOXX

Small-caps have been in a long-term, secular bear market relative to large-caps since 2011. While large-caps and small-caps have gone through multiple rounds of being in and out of favor (13 in the last 100 years, by our count), the current one is the longest on record.

7-28-26-NVDA

We are approaching the one-year anniversary of the small-caps’ 25-year low versus large-caps. Since then, small-caps have outperformed large-caps by as much as 18%, depending on the benchmark. Those types of small-cap surges are traditionally reserved for the beginning of economic expansions, when small-caps are often deeply oversold, or the start of small-cap secular bulls.

West Texas intermediate crude oil futures fell more than 2%, trading around $80.50 per barrel. The 10-year Treasury yield dropped 4 basis points to around 4.6%.

176 companies are reporting this week.

Of the 143 companies that have reported so far (29% of the S&P 500):

  • Overall, 87% are beating estimates, and those that “beat” are beating by a median of 7%.
  • Of the 12% missing, those are missing by a median of -2%.
  • On the top line, overall results are beating estimates by a median of 3% and missing by a median of -2%, and 79% of those reporting are beating estimates.

Tech Selling – We’ll Take the Chips with the Dip

7-8-26-SPX

Technology stocks endured another round of harsh selling on Tuesday, shoving the Nasdaq composite below the 26,000 level again as it fell 1.2%. But the selling was focused on the Nasdaq-100 index, which gapped below its 50-day moving average and dropped 1.8% as sellers hit semiconductor stocks hard for the second straight session.

7-8-26-SOXX

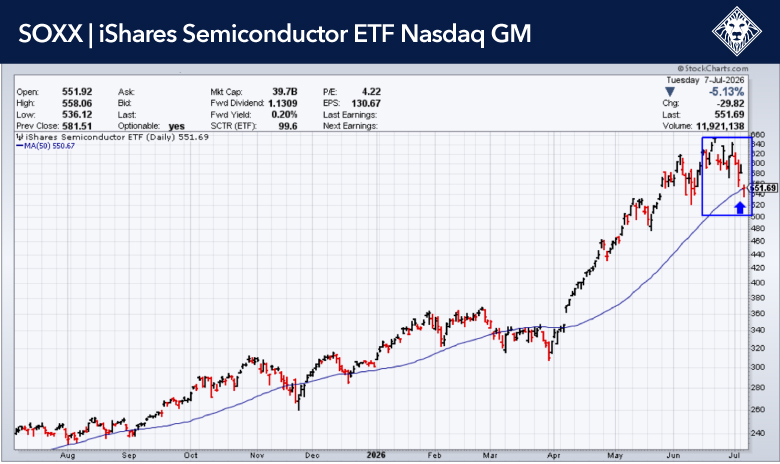
The iShares Semiconductor ETF (SOXX) has pulled back to it 50 days moving average, but is still in an uptrend. Visa (V) has pulled back and looks to be holding at its 50 DMA along with Cognex Corporation (CGNX). We think both look tradable at current levels.

7-8-26-V
7-8-26-CGNX

U.S. economic data points to resilient demand alongside still-elevated inflation, reinforcing expectations for a cautious but continued Federal Reserve tightening path. While easing energy prices following the de-escalation of the Iran conflict should slow headline inflation, core inflation is likely to remain sticky near 3.5%.

The U.S. dollar strengthened materially, supported by widening interest rate differentials as expectations moved toward relatively tighter U.S. policy compared to other major economies.

Over the past month, technical conditions have improved as earlier divergences resolved, reinforcing the view that any near-term pullbacks should be seen within an ongoing bull market. Broad participation remains supportive, with over 60% of stocks trading above their 200-day moving averages, and historical patterns suggest further upside following strong quarterly gains. Sentiment remains broadly neutral, though pockets of speculative behavior have intensified, highlighted by record margin debt levels and elevated use of leverage.


Move Over Tech! Is the Rest of the Market Finally Waking Up?

Markets moved higher last Thursday off the news from President Trump that the conflict in Iran was nearing an end. The rally continues to broaden, as Equal-weight Industrials and Utilities break out and should help Financials and Discretionary show some good participation over the next 1-2 months.

As of this writing, the text of the deal has not been released, and a full re-opening of the Strait of Hormuz will likely take weeks. Nevertheless, the markets took the news as a significant step. On Monday, the S&P 500 jumped 1.7%, and WTI futures plunged 4.2%.

6-17-26-WTIC

At the beginning of the conflict, most commodity strategists predicted oil prices would have been much higher if the Strait had remained closed for 3.5 months. WTI futures’ 15% drop from its May 15 high to June 12 reflects expectations of an eventual re-opening, as well as the global supply chain being more flexible than anticipated.

Even after the June 12 drop, WTI futures are 16% above where they closed on February 27. More confidence in a lasting peace could turn the six-month momentum negative later this summer, when the S&P 500 has risen at an 18.5% annual rate, on average.

Energy prices have been the main culprit for our headline inflation indicator turning bearish in April. A reversal could push the CPI below its six-month average, re-establishing the disinflation that has defined the cyclical bull market that started in late 2022.

6-17-26-PWR

Three stocks we are monitoring are Quanta Services (PWR), which we believe is starting to break out of a flag pattern, Cummins Inc. (CMI), which also looks like it is ready to move higher with lots of demand for Cummins engines as data center construction is mounting, and Hilton Worldwide Holdings (HLT).

6-17-26-HLT

Watch Vance Howard on the Morning Call Sheet: Fed focus meets AI optimism and inflation debate

Vance Howard on CNBC 6-17-26
Torsten Slok, Chief Economist at Apollo Global Management, Vance Howard, CEO and Portfolio Manager at Howard Capital Management, and Gilbert Garcia, Owner of Garcia Hamilton & Associates, discuss Fed policy, inflation risks, AI driven growth, rate outlooks and market strength.
 

Privacy Settings
We use cookies to enhance your experience while using our website. If you are using our Services via a browser you can restrict, block or remove cookies through your web browser settings. We also use content and scripts from third parties that may use tracking technologies. You can selectively provide your consent below to allow such third party embeds. For complete information about the cookies we use, data we collect and how we process them, please check our Privacy Policy
Youtube
Consent to display content from - Youtube
Vimeo
Consent to display content from - Vimeo
Google Maps
Consent to display content from - Google